A separate deduction from cost segregation, on a separate basis. The 2025 law closed it to property whose construction begins after June 30, 2026, so the question now is which of your projects began in time.
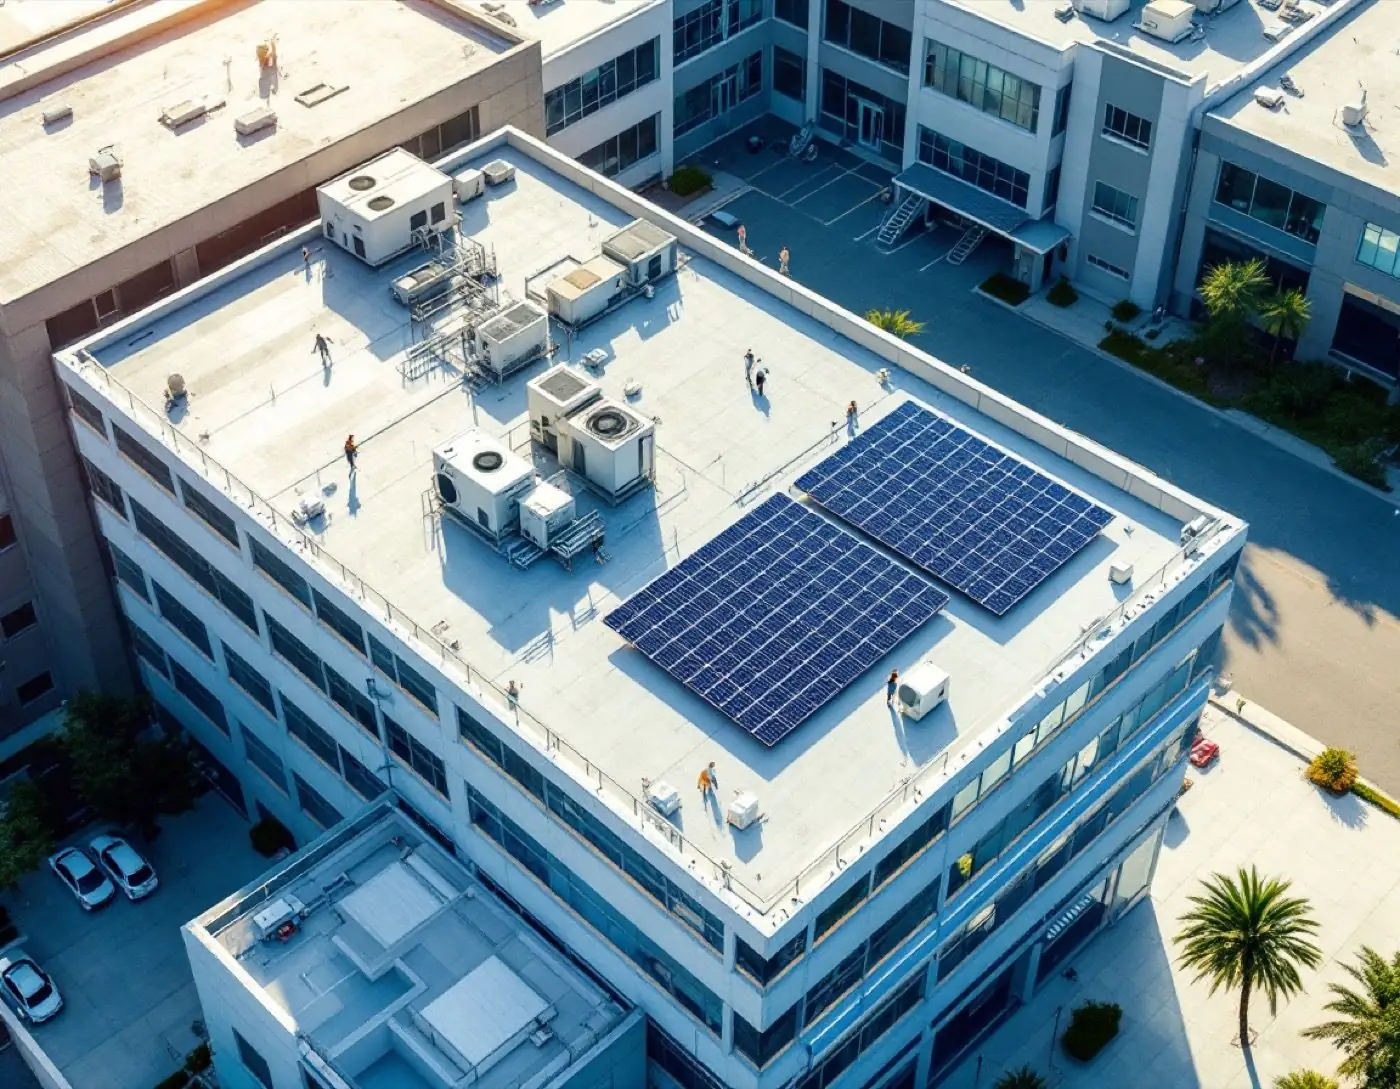
Section 179D provides a deduction for energy-efficient commercial building property: interior lighting, HVAC and hot water systems, and the building envelope, measured against a reference standard by qualified energy modeling. Because it is calculated per square foot, it is meaningful on large-footprint assets.
The 2025 law added a termination date: 179D does not apply to property whose construction begins after June 30, 2026. Projects that began on or before that date can still qualify, so the first question on any 179D engagement is when construction began.
Is the project still eligible?The June 30, 2026 construction cutoff
Construction began on or before June 30, 2026
The project may still qualify when it is placed in service, subject to the modeling, verification and certification requirements.
Construction began after June 30, 2026
179D does not apply. The 2025 law ended the deduction for property whose construction begins after that date.
Building areaSquare feet
×
Rate per square footSet by modeled savings
=
Deduction179D
Interior lighting HVAC and hot water Building envelope
Savings are measured against a reference standard by qualified energy modeling, then verified on site. The higher rate depends on prevailing wage and apprenticeship requirements.
Owners claim it. Designers can be allocated it.
Building owners
On your own building
If you own a commercial building whose lighting, HVAC or envelope beats the reference standard, and its construction began in time, the deduction is yours in the year the property is placed in service. We confirm the construction start before modeling anything.
Architects, engineers, design-build
On government and tax-exempt projects
When the building belongs to an entity that cannot use a deduction, it may be allocated to the designers responsible for the efficient systems. We manage the allocation-letter process with the owning entity.
Coordinated, so nothing is counted twice
179D and a cost segregation study are taken in addition to each other, but the interaction has to be handled correctly. Basis reduced by a 179D deduction is not also depreciated.
Qualified modeling and certification
Energy modeling by a qualified professional, a field inspection confirming the modeled systems are the installed systems, and a signed certification.
Documentation for the higher rate
The increased deduction is tied to prevailing wage and apprenticeship requirements. We review the available documentation before modeling to the higher tier.
One schedule, both deductions
Where 179D runs alongside a study, the fixed asset schedule already reflects the basis reduction, so the two never overlap.
For property whose construction began on or before June 30, 2026, it can be. The 2025 law ended the deduction for property whose construction begins after that date. Whether a specific project qualifies turns on when its construction began, which we confirm before any modeling.
Is 179D instead of cost segregation, or in addition?
In addition, but the interaction has to be handled correctly, because basis reduced by a 179D deduction is not also depreciated. We coordinate both so nothing is counted twice.
We are an architecture firm, not a building owner. Do we qualify?
Possibly, for the design of buildings owned by government or tax-exempt entities. The deduction has to be allocated to you by the owner, and that process has requirements we manage.
Does the higher deduction rate require anything extra?
Yes. The increased deduction is tied to prevailing wage and apprenticeship requirements. We review the available documentation before modeling to the higher tier.
Engineering will review the property and send your written estimate and proposal within 24 to 48 hours. Preview site: this form is not yet connected, so nothing was sent.